What Is an Emergency Fund? How to Start Saving for Surprise Costs
What Is an Emergency Fund? How to Start Saving for Surprise Costs
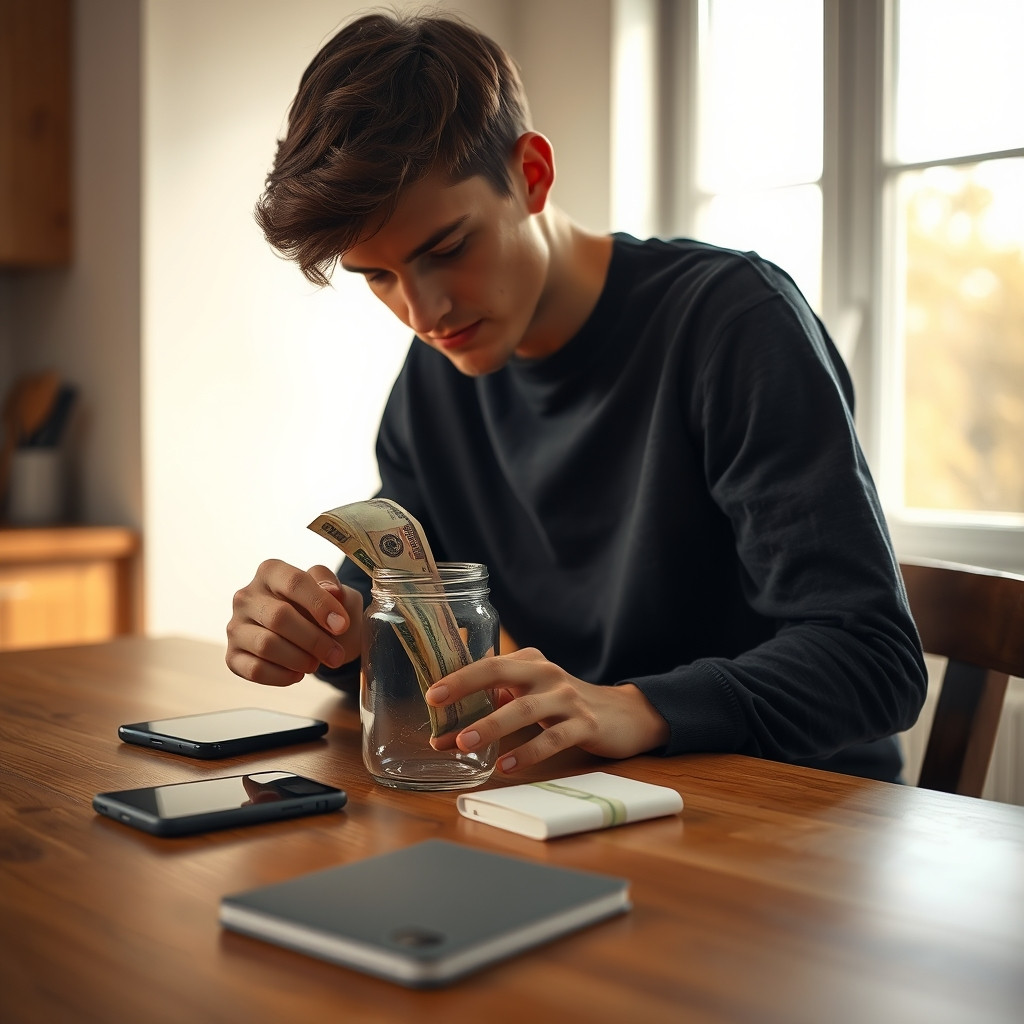
Life is full of surprises. Your phone breaks. Your bike needs a repair. A doctor visit costs more than you planned. Or your income stops for a while. An emergency fund helps you handle these moments without panic.
Quick answer: An emergency fund is money you save only for surprise costs, like repairs, medical bills, or losing your income. Start small. Set a goal, save a little on a regular schedule, and keep the money somewhere safe and easy to reach. Use it only for real emergencies, and refill it after you use it.
What Is an Emergency Fund?
The U.S. Consumer Financial Protection Bureau (CFPB) explains it simply. An emergency fund is "a cash reserve that's specifically set aside for unplanned expenses or financial emergencies."
Common examples include:
- Car or bike repairs.
- Home repairs, like a broken pipe.
- Medical bills.
- Losing your job or income.
This money is not for shopping, trips, or gifts. It is your safety net.
Why Do You Need an Emergency Fund?
Without savings, even a small surprise cost can cause big trouble. As the CFPB guide, shared by NC State Extension, puts it: "Without savings, a financial shock—even minor—could set you back."
When people have no savings, they often turn to credit cards or loans. Interest and fees can make the cost much bigger than it was at first. Some people also take money out of long-term savings, which can hurt their future plans.
An emergency fund helps you:
- Pay surprise bills without borrowing.
- Avoid high-interest debt.
- Feel calmer about money.
- Keep your long-term savings safe.

How Much Should You Save?
There is no single right number. The CFPB says the right amount "depends on your situation."
Here is a simple way to choose a goal:
- Look back. Think about surprise costs you had in the past year. How much did they cost?
- Set a first goal. Start with a small target, like enough to cover one surprise repair.
- Grow over time. Many money experts suggest working toward a few months of basic living costs. This is a common rule of thumb, not a strict rule.
Remember: even a small amount helps. Having some savings is much better than having none.
How to Build an Emergency Fund: 5 Simple Steps
Step 1: Make a Savings Habit
Set a clear goal and save a set amount on a regular schedule. Check your progress, and celebrate when you reach a milestone. Small, steady steps add up.
Step 2: Watch When Money Comes In and Goes Out
Look at when you get paid and when your bills are due. In weeks when you have more money left over, move some into savings. If you have a budget, add savings as one of your regular "bills."
Step 3: Save Surprise Money
Got a tax refund, a gift, or a bonus? Put all or part of it into your emergency fund. The CFPB says that if saving is hard for you, managing your cash flow or saving part of your tax refund are "the easiest ways to get started."
Step 4: Save Automatically
Set up an automatic transfer from your main account to your savings each payday. If you never see the money, you are less likely to spend it. Just watch your balance so you do not overdraw your account.
Step 5: Split Your Pay
Some employers let you send part of your pay straight to a savings account. Ask your employer or bank if this is possible.

Where Should You Keep Your Emergency Fund?
Your emergency fund should be safe and easy to reach, but not so easy that you spend it by accident. The CFPB lists three options:
| Option | Good Points | Things to Watch |
|---|---|---|
| Bank or savings account | Generally one of the safest places for money | Keep it separate from your spending account |
| Prepaid card | You can only spend what is loaded on it | Check for fees |
| Cash at home | Fast to reach | Can be lost, stolen, or damaged |
For most people, a separate savings account at a trusted bank is a smart choice. In many countries, deposits at licensed banks have some protection. Check the rules where you live.
When Should You Use It?
Decide ahead of time what counts as an emergency. Ask yourself three questions:
- Is it unexpected?
- Is it necessary?
- Is it urgent?
If the answer to all three is yes, it is likely a real emergency. A broken phone you need for work may count. A new phone because a new model came out does not.
Do not feel guilty about using the fund when you truly need it. That is what it is for. Just make a plan to refill it afterward.

Easy Ways to Find Money to Save
- Cancel subscriptions you do not use.
- Cook at home a few more times each week.
- Save any money left at the end of the month.
- Sell things you no longer need.
- Earn a little extra with a side skill or small online sales.
If you have items to sell or a service to offer, the WeConectus Marketplace lets members list products and services. Any extra money can go straight into your fund.
For more help with planning, the CFPB also shares free budgeting strategies and tools. You can also find more simple guides on WeConectus.
Frequently Asked Questions
What is an emergency fund?
It is money saved only for surprise costs, like repairs, medical bills, or a loss of income. It is your financial safety net.
How much should be in an emergency fund?
It depends on your life and costs. Start with a small goal, like one surprise repair. Then slowly work toward a few months of basic living costs.
Where is the best place to keep an emergency fund?
A separate savings account at a trusted bank is a good choice for most people. It keeps the money safe and apart from your daily spending.
Should I save or pay off debt first?
Many people do both. A small emergency fund can stop you from adding new debt when a surprise cost comes. Then you can focus more on paying down debt.
What counts as an emergency?
A cost that is unexpected, necessary, and urgent. Examples include a needed repair, a medical bill, or a sudden loss of income.
How can I save if I earn very little?
Start with tiny amounts. Save part of any surprise money, like a gift or refund. Even small, regular savings can grow over time.
What should I do after I use my emergency fund?
Make a plan to refill it. Go back to saving a small amount on a regular schedule until you reach your goal again.
Final Thoughts
An emergency fund gives you peace of mind. You do not need a lot of money to start. Set a small goal, save on a schedule, and keep the money in a safe place. Use it only for real emergencies, and refill it when you can. Step by step, you can build a safety net for life's surprises.
This article is for general education only and is not personal financial advice. Banking rules and protections differ by country. For advice about your own situation, speak with a qualified financial professional.


